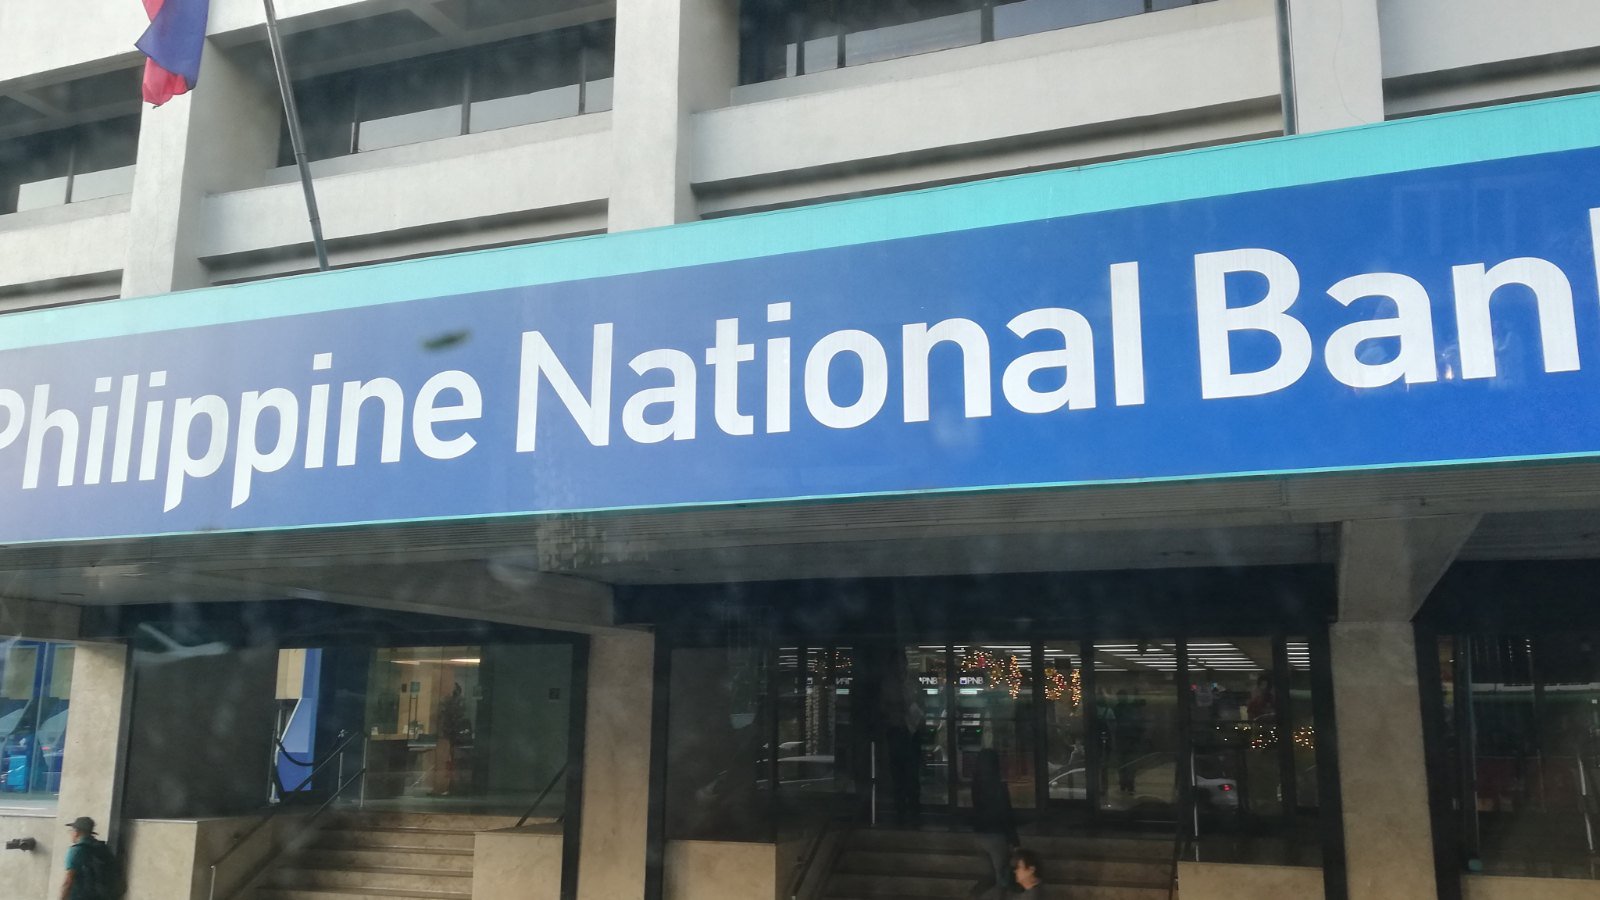
Philippine National Bank (PNB) expects to keep growing at a double-digit pace in the second half of the year, according to president and CEO Edwin Bautista. He said the bank’s low-cost deposit base and its focus on business lending should soften the effect of rising interest rates. Bautista declined to give a specific growth forecast but said the momentum from the first half has continued into the following months.
“But so far the trend continues,” Bautista said, adding that growth rates should look very similar to the first half. PNB’s net income for January to June reached P14.6 billion, up about 17 percent from P12.5 billion a year earlier.
Bautista’s case rests largely on how the bank is funded. PNB has a high ratio of current and savings accounts, backed by a wide branch network, and he said that mix should keep funding costs fairly stable even as rates go up. Only a small share of its deposits are time deposits that would need to pay higher interest, he explained. At the same time, higher benchmark rates could let PNB charge more on its loans, which would help lending margins.
He acknowledged the downsides. Rising rates can cut the value of the bank’s bond holdings and produce net unrealized losses that hit capital, and PNB is still exposed to that risk. Bautista pointed to the bank’s capital adequacy ratio of about 20 percent as the answer. “The difference is our buffer is so fat that it will hardly matter,” he said.
Credit quality is the other area to watch. Bautista said higher interest rates and inflation could squeeze borrowers’ finances and lead to more past-due loans. That matters for PNB because companies and businesses make up 92 percent of its loan book, so its results depend heavily on how corporate borrowers handle the tighter conditions in the months ahead.